VAT on client gifts in France: the €73 threshold, the maths and a clothing gift box
French businesses can recover the VAT on a client gift as long as its value stays within €73 including VAT per client per year (French tax code, annex IV, article 28-00 A). A box with an embroidered sweatshirt, t-shirt and tote bag costs €66.90 incl. VAT on tknp.io for 25 boxes: it stays under the threshold, and €11.15 of VAT comes back to you per box.
Giving your clients something good at the end of the year is one of the gestures that count most in a business relationship. When that gift is personalised merch carrying your logo, you still need to know what it really costs, VAT included. The French rule is short, but the maths has traps: shipping, a box that brings several items together, a client who gets two gifts in the same year.
The texts quoted here were read on 11 November 2026 on Legifrance, the French government's legal database, and in the Bulletin officiel des finances publiques (BOFiP), the official guidance of the French tax administration. They describe the French rule. It is information, not tax advice from your accountant. On the clothing side, every amount comes from our tknp.io product pages, checked on that same 11 November.
What is the VAT limit on client gifts in France?
The limit is €73 including VAT per item and per year for the same recipient. Article 28-00 A of annex IV of the French tax code (Code général des impôts), in force since 12 June 2021, defines "goods of very low value" as those whose unit value does not exceed €73 including VAT per item and per year for the same recipient.
That threshold is an exception. The principle, set in article 206 of annex II of the same code (IV, 2, 3°), is that VAT on goods handed over for nothing, gifts included, cannot be deducted, except for goods of very low value. The BOFiP (BOI-TVA-DED-30-30-50) adds that this exclusion applies whoever the recipient is, and even when the operation is carried out in the interest of the business.
Above €73 incl. VAT you can still give the gift: you simply keep its VAT as a cost.
What counts towards the €73?
The €73 of a client gift covers its purchase price including VAT, the cost of getting it there and every gift given to the same client that year. The BOFiP details these three points, which often change the result.
- The purchase price including VAT, not the retail price: the value used is the price the giving company paid, or the cost price if you have the item made, and the amount is assessed including VAT.
- The cost of getting it there: distribution costs borne by the company always count, packaging and shipping in particular. The share of shipping on your order counts, and so does sending the gift to the client.
- The whole box and the whole year: a set of several items that could be given separately counts at the total value of the set. And when you give several times to the same client, the gifts of the year added together must stay under the threshold.
A cap given in June and a box given in December to the same client are therefore added up. Keep a table per client, with the date, the gift and its amount, filed with the invoices: it proves the threshold was respected.
How do you calculate the recoverable VAT on a client gift?
The sum takes four steps, for each client.
- Take the purchase price of the gift excluding VAT, for the whole box.
- Add the share of shipping and packaging that belongs to that gift.
- Convert to the price including VAT: in France the standard VAT rate is 20% (tax code, article 278).
- Add any other gifts given to the same client that year, then compare with €73.
If the total stays at €73 incl. VAT or less, the VAT paid on that gift can be recovered, with the invoice as proof. Above that, it cannot be recovered on any part of the gift. A business under the VAT exemption scheme for small businesses (franchise en base, a French micro-entrepreneur for instance) does not face the question: impots.gouv.fr points out that it cannot recover VAT on its business purchases.
A real case: an embroidered sweatshirt, t-shirt and tote bag box
A box of three embroidered textiles fits under the €73 VAT threshold, as long as you pick the right models. The amounts below, read on 11 November 2026 and given as a guide, assume one 8 x 10 cm embroidered logo placed once, the model's most affordable shade, standard sizes, two weeks of production, and no shipping yet.
| Embroidered item (tknp.io page) | Excl. VAT, 10 | Excl. VAT, 25 | Incl. VAT, 25 |
|---|---|---|---|
| Radder 2.0, Stanley/Stella organic crewneck (350 g/m²) | €36.37 | €34.57 | €41.48 |
| Creator 2.0, Stanley/Stella organic t-shirt (180 g/m²) | €12.65 | €11.82 | €14.18 |
| Gallery Canvas Tote bag, Westford Mill, 407 g/m² canvas | €10.01 | €9.36 | €11.23 |
| Cultivator 2.0, organic hoodie in 350 g/m², Stanley/Stella | €43.99 | €41.85 | €50.22 |
Price per garment or bag excluding VAT, embroidery included, read on 11 November 2026; VAT-inclusive price calculated at 20%.
For 25 boxes of Radder sweatshirt, t-shirt and tote: €55.75 excl. VAT per box, i.e. €66.90 incl. VAT. Shipping for an order delivered in France is a flat €15.00 excl. VAT, i.e. €18.00 incl. VAT, shared across the 25 boxes: €0.72 each. Total: €67.62 incl. VAT, €5.38 under the threshold, before sending each box to the client. The recoverable VAT is €11.15 per box, €278.75 for all 25.
For 10 boxes, the same trio costs €59.03 excl. VAT, i.e. €70.84 incl. VAT, plus €1.80 of shipping: €72.64 incl. VAT. That leaves €0.36 of headroom. If you then post each box, the stamp will almost certainly push it over: in that case hand the boxes over in person, or go up to 25.
With the hoodie, the result flips. A box with the Cultivator 2.0, the t-shirt and the tote costs €63.03 excl. VAT for 25, i.e. €75.64 incl. VAT before shipping even starts: €12.61 of VAT per box stays as a cost, i.e. €315.15 for 25 clients, worked out on the €1,575.75 excl. VAT total (the per-box amount is rounded to the cent). To keep the recovery, pick the crewneck, or give the hoodie on its own (€50.22 incl. VAT).
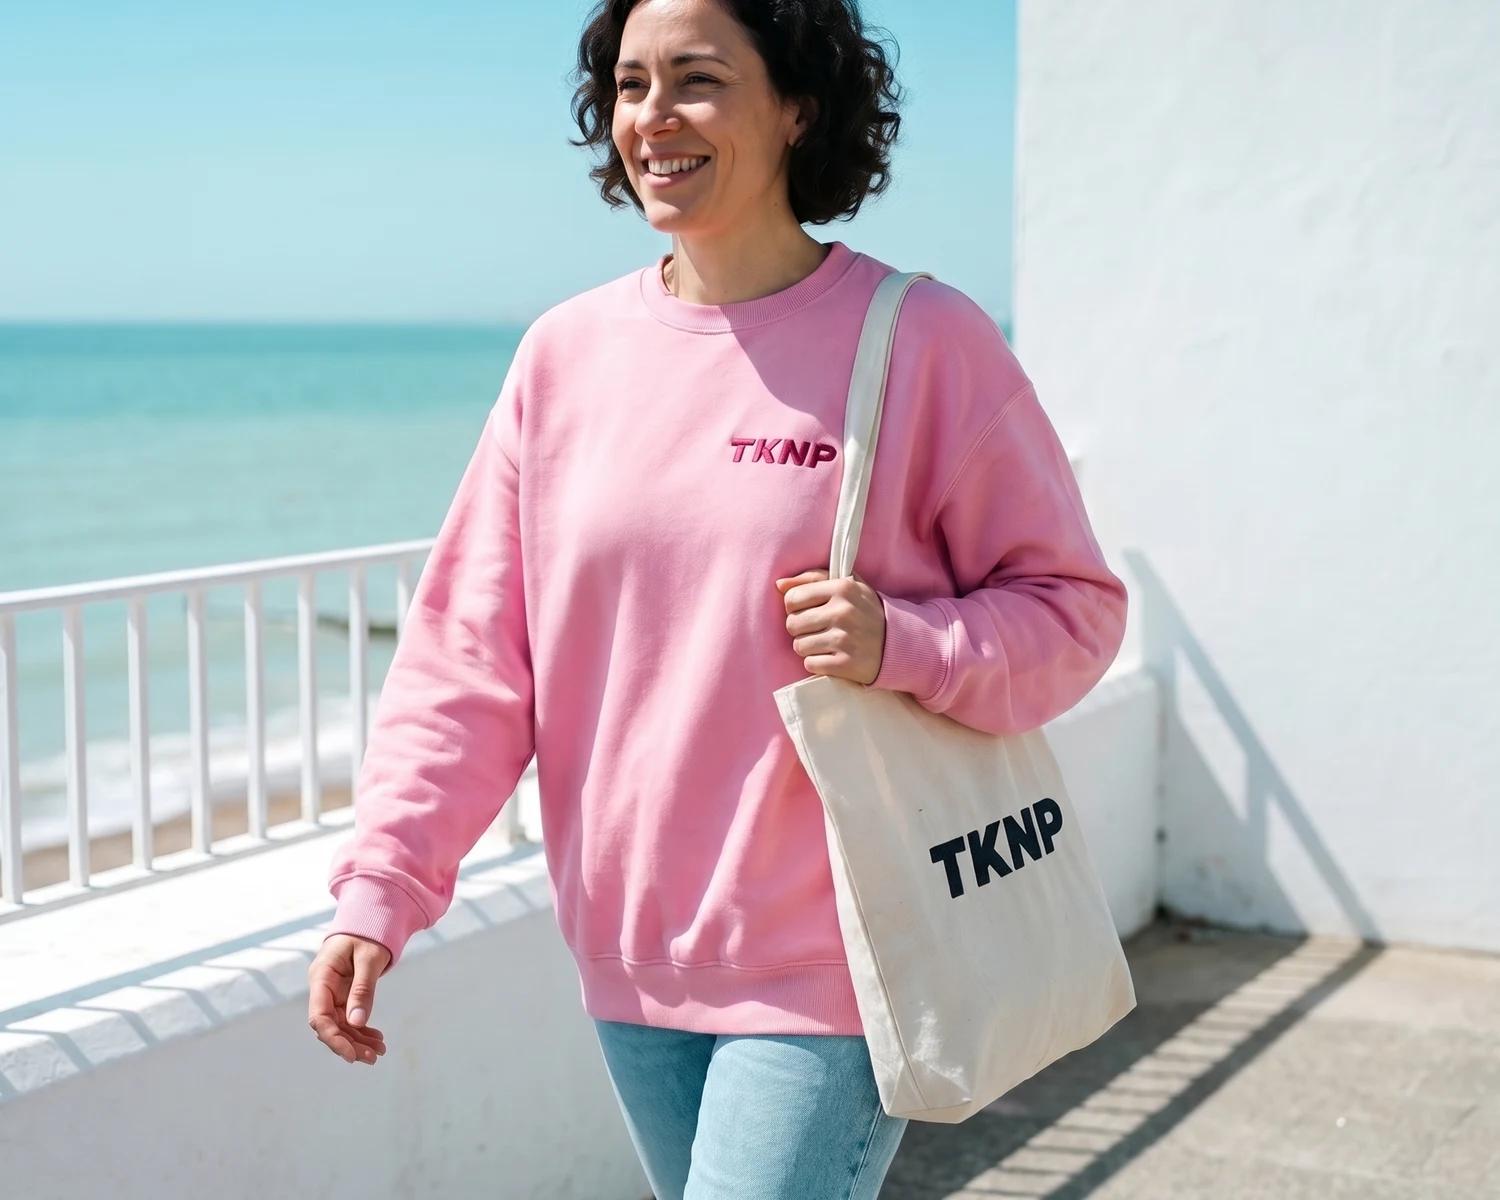
Two details on the product page can move these amounts. First, the brand charges more for a few shades and the very biggest sizes: the page shows the difference as soon as you select them. Second, the tier adds up every unit of one model, even across several shades, provided the embroidered logo stays identical: our guide to volume pricing explains how it is counted. The Pink Joy in our photo, the pink of the Radder 2.0, is one of that model's colours.
Know the VAT-inclusive price of your gift before you order
On every tknp.io product page, the price shown for each quantity already includes the embroidery: multiply it by 1.20 and you know, before paying, whether your box stays under €73. The Shipping tab of the same page gives the rate for your country, a flat fee per order whatever the quantity. A box that goes beyond the catalogue is priced separately: our FAQ promises an answer within 24 working hours, through this page. And our guide to hidden costs lists what a textile quote must show for this sum to stay accurate.
To choose the gift itself, the budget per client and how to give clothing to someone whose size you do not know, see our ideas for a client gift.
The statement of general expenses: the income tax rule next to VAT
Once gifts exceed €3,000 over the financial year, a French business declares them on the statement of general expenses (relevé des frais généraux): that is article 4 J of annex IV of the French tax code, in force since 2 February 2025. This rule belongs to business income tax, not VAT. According to the BOFiP (BOI-BIC-CHG-40-60-10), a company fills it in on form 2067-SD; a sole trader on the actual-profit regime uses a box in annex 2031 bis-SD.
Items specially designed for advertising, with a unit value of €73 incl. VAT or less, do not count towards that €3,000. The BOFiP describes them as carrying a visible and permanent inscription of the company's name, legible when the item is used normally. An embroidery on the chest reads clearly; with a logo embroidered in the fabric's own colour, deliberately quiet, ask your accountant whether it qualifies. This point concerns the statement, not VAT: the VAT threshold itself requires no inscription.
Does the rule change in 2027?
The French VAT rule on client gifts does not change in substance in 2027: only its references do. On 1 January 2027, French VAT rules move from the Code général des impôts to the code des impositions sur les biens et services; in its news item of 7 October 2026, the BOFiP states that the tax administration's guidance remains unchanged, and the old references can still be used until 30 June 2028. The €73 threshold itself has not moved since 2021: the BOFiP notes that it is reviewed every five years in line with the consumer price index excluding tobacco (order of 12 October 2005, article 3).
Frequently asked questions
Why do some pages still mention a €65 threshold?
Because they have not been updated. On 11 November 2026, the impots.gouv.fr page on deducting VAT on purchases, last modified on 14 October 2026, still says €65 incl. VAT. The text in force, article 28-00 A of annex IV of the French tax code, has said €73 incl. VAT since 12 June 2021.
Does the €73 rule apply to a gift given to an employee?
For VAT, yes: the BOFiP applies the exclusion whoever the recipient is, client, partner or employee. Social security contributions on a gift from the employer follow another rule, set by the Urssaf. What to give the team, and how to put together each person's box: that is what our page on end-of-year company gifts covers.
Does a free sample count towards the €73?
No, if it is a genuine sample: the BOFiP defines it as an item whose packaging makes it unfit for sale, and giving it away does not affect the deduction, whatever its value. A full sweatshirt or t-shirt given to a client is not a sample: it is a gift.
Does this rule apply in Belgium or Switzerland?
No, it is French. Belgium and Switzerland have their own VAT rules on business gifts, which we do not cover here: ask the tax office of the country concerned, or your accountant, before you rely on a threshold.
Your project, quoted within 24 hours.
Describe your garments, your decoration and your quantities: you receive a detailed quote, decoration included, within one business day.